Credit card processing is an essential component of modern commerce, enabling businesses to accept electronic payments from customers. Whether you’re a business owner or a consumer, understanding the ins and outs of credit card processing is crucial. In this article, we will provide you with everything you need to know about credit card processing, including its key players, the transaction process, security measures, and associated fees.
Credit card processing refers to the mechanism by which businesses accept credit card payments from customers. It involves the secure transfer of funds from the customer’s credit card processing to the merchant’s bank account. The process includes authorization, capturing, clearing, and settlement of the transaction.
2. Key Players in Credit Card Processing
Several entities play key roles in credit card processing:
- Merchant: The business or individual accepting credit card payments from customers.
- Cardholder: The consumer who owns and uses a credit card for purchases.
- Acquiring Bank: The financial institution that partners with merchants to enable them to accept credit card payments.
- Card Association: Organizations such as Visa, Mastercard, American Express, and Discover that set the rules and regulations governing credit card transactions.
- Issuing Bank: The financial institution that issues credit cards to consumers and is responsible for authorizing and processing transactions on behalf of cardholders.
- Payment Processor: Companies that facilitate credit card transactions by providing the technical infrastructure and services necessary for the authorization, settlement, and security of payments.
3. The Credit Card Transaction Process
The credit card transaction process involves several steps:
- Authorization: When a customer makes a purchase using a credit card, the merchant sends an authorization request to the acquiring bank through the payment processor. The acquiring bank verifies the transaction’s validity by communicating with the card association and the issuing bank.
- Capturing: Once the transaction is authorized, the merchant captures the transaction details, including the amount, and prepares it for settlement.
- Clearing: The merchant’s acquiring bank sends the transaction details to the card association for clearing. The card association facilitates the transfer of funds from the issuing bank to the acquiring bank.
- Settlement: The acquiring bank deposits the funds into the merchant’s designated bank account. The settlement process ensures that the merchant receives payment for the transaction.
4. Security Measures in Credit Card Processing
To ensure the security of credit card transactions, various security measures are employed:
- Encryption: Sensitive cardholder data is encrypted during transmission and storage to protect it from unauthorized access.
- Tokenization: Tokenization replaces cardholder data with unique tokens, minimizing the risk of data breaches as the tokens are useless to hackers.
- PCI DSS Compliance: The Payment Card Industry Data Security Standard (PCI DSS) is a set of security requirements that businesses must adhere to when processing credit card payments. It ensures the secure handling, transmission, and storage of cardholder data.
- Fraud Detection: Advanced fraud detection systems analyze transaction patterns and behaviors to identify and prevent fraudulent activities.
5. Understanding Credit Card Processing Fees
Credit card processing fees vary depending on various factors:
- Interchange Fees: These are fees paid to the cardholder’s issuing bank and are set by the card associations. Interchange fees are based on transaction type, card brand, and business category.
- Assessment Fees: Assessment fees are charged by the card associations to cover their operational costs. They are typically a percentage of the transaction value.
- Processor Markup: Payment processors charge a markup fee for their services, including transaction processing, risk management, customer support, and technology infrastructure.
- Additional Fees: Other fees may include setup fees, monthly fees, chargeback fees, and termination fees. These fees can vary among payment processors.
6. Choosing a Credit Card Processor
When selecting a credit card processor, consider the following:
- Cost and Fees: Compare rates, fee structures, and additional charges among different processors to ensure competitive pricing.
- Security and Compliance: Ensure the processor adheres to security standards, such as PCI DSS compliance, to protect customer data.
- Integration and Compatibility: Choose a processor that integrates smoothly with your existing systems, such as e-commerce platforms or point-of-sale (POS) systems.
- Customer Support: Evaluate the level of customer support provided by the processor to ensure prompt assistance in case of issues or inquiries.
7. Integration with Payment Gateways
Payment gateways act as intermediaries between the merchant’s website or POS system and the payment processor. They securely transmit payment data, such as credit card information, to the processor for authorization and settlement. Integration with a reliable payment gateway is crucial for smooth and secure credit card processing.
8. Online vs. In-person Credit Card Processing
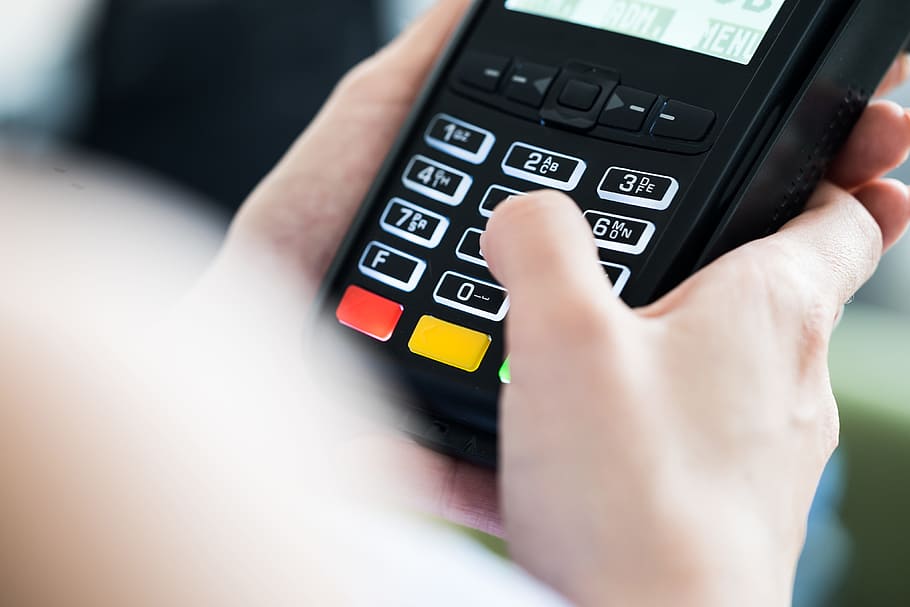
Online credit card processing involves accepting payments through e-commerce websites or online payment gateways. In-person credit card processing, often used in retail stores or physical businesses, utilizes card readers or POS systems to accept payments. Each method has specific considerations, such as security, user experience, and hardware requirements.
9. Mobile Credit Card Processing
Mobile credit card processing enables businesses to accept payments using mobile devices, such as smartphones or tablets. It is particularly useful for on-the-go businesses, events, or service providers. Mobile payment solutions typically involve card readers or mobile wallet apps that securely process transactions.
10. The Future of Credit Card Processing
The future of credit card processing is expected to witness advancements in technology, security, and payment experiences. Trends such as contactless payments, biometric authentication, blockchain integration, and enhanced data analytics will shape the industry, providing businesses and consumers with more convenient, secure, and personalized payment options.
Conclusion
Credit card processing is a critical aspect of modern commerce, enabling businesses to accept electronic payments and providing consumers with convenient payment options. By understanding the key players, transaction process, security measures, and associated fees, businesses and consumers can navigate the world of credit card processing more effectively. Stay informed about industry trends, choose a reliable credit card processor, prioritize security, and optimize the payment experience to ensure a seamless and secure credit card processing journey for all parties involved.